

Workday is undergoing its second round of layoffs this year, with approximately 500 employees being affected this time. The company has also lowered its financial profit forecasts for the third quarter.
The software as a service giant stated in a securities document on Tuesday that it will cut about 2.5% of its workforce, mainly from the product and technology teams, in order to “better align the team structure with the strategic growth priorities of Workday.”
The company stated that as of the end of January, it had a total workforce of over 21,000 employees and plans to continue hiring in strategic areas and regions throughout the 2027 fiscal year.
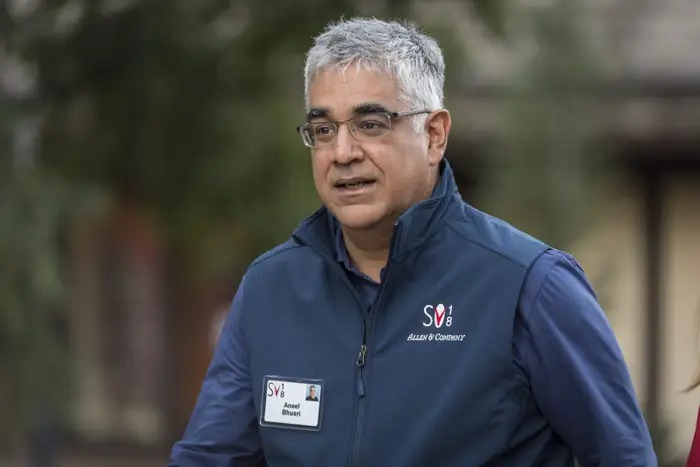
Workday laid off about 400 people in February this year, and about a week later, the then CEO Carl Eschenbach resigned. Subsequently, Workday, co-founder and executive chairman Aneel Bhusri, took over. He had previously held the company's highest position three times before.
In both rounds of layoffs, Workday did not cite artificial intelligence as a triggering factor; however, earlier this year, this technology once dampened investors' interest in the company and other enterprise software providers. At that time, what was known as “SaaSpocalypse” caused billions of dollars to be wiped off the market value of these companies due to concerns that artificial intelligence might lead enterprises to develop their own software rather than purchasing it.
Bhusri remains optimistic about the company's prospects. During a financial report conference call with analysts in August, he stated, "Last quarter, I told you that I hadn't encountered a single customer who wanted to replace Workday with something developed in-house or purchased from a startup. A quarter has passed, and this situation hasn't changed." Workday also said on Tuesday that the reorganization costs resulting from the latest round of layoffs will lower its operating profit margins for the third quarter and the entire year of fiscal 2027.