

As the supply of Bitcoin gradually approaches the upper limit of 21 million coins, how many Bitcoins are actually in circulation within the economic system? Millions of BTC have not been used for many years, while ETF, corporate treasuries, and lending markets are changing the way these assets are held and allocated. The gap between the total supply of Bitcoin and the "economically active supply" raises a key question: How many BTC are actually available for trading, and how many are being put into use? This report assesses the efficiency of the utilization of Bitcoin's existing supply by analyzing its dormant supply, market liquidity, institutional holdings, and financial deployment.
Bitcoin Supply Split: How much of the BTC actually has liquidity?
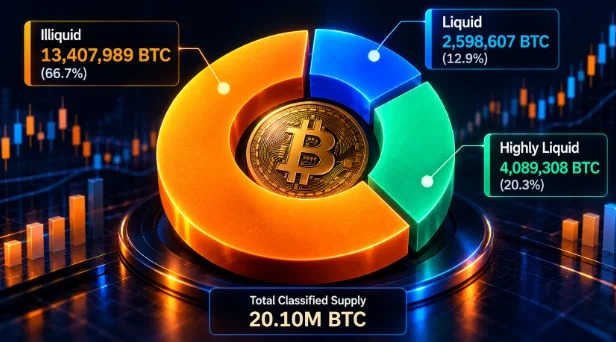
Illiquid supply accounts for approximately 66.7% of the total measured amount, which is about 13.41 million BTC. The combined liquid and highly liquid supply amounts to about 6.69 million BTC, indicating that the portion related to higher-level spending activities is significantly smaller within the classified supply.
Bitcoin Dormant Supply: How many BTC have not been transferred in the past five years?
The dormant supply of Bitcoin highlights the scale of long-term holdings across the entire network. Approximately 6.84 million BTC coins have not been transferred for at least five years, accounting for about 34.1% of the measured supply. Of these, over 3.63 million Bitcoin coins have not been moved for more than 10 years.
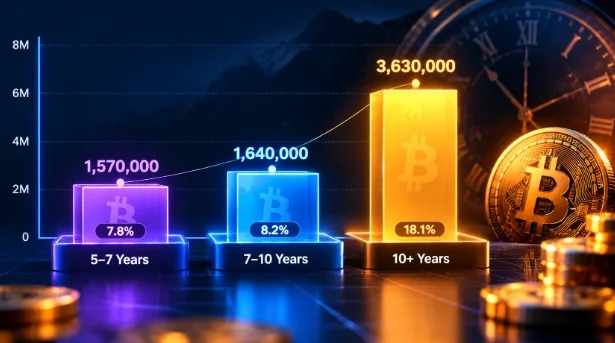
This group of "over 10 years" accounts for more than half of those who have not moved their BTC for at least five years. This indicates a high degree of concentration of Bitcoin held for a long time. However, the fact that these accounts are dormant does not prove whether these coins have been permanently lost, securely held, or may re-enter circulation in the future. Tracking changes in these age segments helps to identify when the previously inactive supply begins to flow again.
Bitcoin Liquidity: How many BTC are held in exchanges?
Exchange balances can reflect the scale of Bitcoin held in identifiable transaction infrastructure. The latest wallet-level data available indicates that the tracked group of exchange wallets holds approximately 733,753 BTC.
A broader estimation of exchange balances may be higher, as different data providers use various wallet identification methods and have different coverage ranges. Exchange reserves help to assess the quantity of BTC held by trading platforms, but the balance itself does not prove the existence of immediate selling pressure. A decrease in reserves may reflect funds being withdrawn to private custody or other wallets, while an increase in reserves may indicate an increase in deposits into the exchanges. These changes need to be interpreted in conjunction with price trends, trading volume, and other market indicators.
Bitcoin ETF Holdings: How much of the supply is held by institutional funds?
US spot Bitcoin ETF provides investors with exposure to Bitcoin through regulated investment funds. In the October dataset cited in the report, these funds held a total of approximately 1.29 million BTC, of which BlackRock's IBIT held about 805,222 BTC, making it the largest fund in that group.
ETF represents the amount of Bitcoin held by a fund, while net flow tracks the changes in investors' funds over a period of time. The directions of change for these two figures may not be consistent: even if a fund experiences net outflows, it may still continue to hold a large balance of BTC. By tracking both holdings and capital flows simultaneously, one can more clearly observe the changes in institutional exposures and investor demand.
Enterprise Bitcoin Holdings and Financial Deployments: Is BTC Being Put into Use?
Corporate treasuries have become an important channel for holding Bitcoin. Strategy held approximately 848,000 BTC at the beginning of October, making it the company with the largest disclosed Bitcoin holdings.
In addition to holding BTC as a reserve asset, Bitcoin can also support borrowing through mortgage credit arrangements. Such markets allow holders to obtain funds without necessarily having to sell Bitcoin.
The latest available data shows that among the credits secured by Bitcoin, approximately 1.175 million BTC have been pledged, supporting debts denominated in US dollars amounting to about 33.21 billion dollars.
The holdings in a corporate treasury and the balance of collateral represent different financial purposes and should be assessed separately. The former measures the amount of Bitcoin owned by the enterprise, while the latter tracks the BTC that is pledged in related credit arrangements. Taken together, these indicators show that Bitcoin can serve both as a reserve asset for enterprises and as collateral in the credit market.
Bitcoin Chain Activity: Are There Really More BTCs in Circulation?
Active addresses can be used to measure participation in the Bitcoin network. On October 8th, Bitcoin recorded approximately 653,121 active addresses, which is an increase of 9.4% from 597,061 on September 8th.
An increase in address activity may reflect a variety of activities, including transactions, payments, exchange settlements, custodial transfers, and wallet management. However, active addresses alone cannot measure the actual quantity of BTC that has been transferred, nor can they prove whether previously dormant bitcoins have returned to circulation. To determine whether an increase in network participation is accompanied by stronger economic activity, it is also necessary to consider adjusted transfer volumes and supply age indicators.
Tracking these indicators alongside the dormant supply helps to reveal whether Bitcoin held for a long time has begun to flow again, or whether there is merely an increase in network activity without any substantial change in the older supply group.
Bitcoin Capital Utilization: Where Exactly Is the Supply Being Used?
The supply of Bitcoin can be assessed from three measurable dimensions: historical spending behavior, market liquidity, and financial deployment. Taken together, these indicators show how BTC is held, how much of it is related to trading infrastructure, and how Bitcoin is used in the financial markets. Dormant supply data tracks long-term holding behavior, exchange reserves measure the amount of BTC stored in identified trading wallets, while mortgage balances reflect the Bitcoin that is pledged in related credit arrangements.
The key lies in tracking the changes of these indicators over time. If the older dormant supply group declines, while exchange balances and transfer activities increase, it may indicate that previously inactive BTC is re-entering circulation. At the same time, an increase in mortgage balances may suggest an increased use of Bitcoin in the credit market. No single indicator can independently depict "utilization rate"; only by observing these indicators together can we gain a more complete understanding of Bitcoin's evolving economic role.
The Utilization Gap of Bitcoin: What Do the Data Indicate?
These data highlight three important characteristics of the Bitcoin supply structure. Firstly, long-term holding is still very significant; approximately 6.84 million BTC coins have not been transferred for at least five years. The illiquid supply accounts for about 66.7% of the measured liquid supply dataset, indicating that a large portion of the classified supply has had limited spending activity over history.
Institutional exposure is another important component. The US spot Bitcoin ETF holds approximately 1.29 million BTC, enabling investors to obtain Bitcoin exposure through investment funds. At the same time, corporate vault holdings and credit arrangements backed by Bitcoin demonstrate how BTC can serve both as a reserve asset and as collateral for loans.
Overall, these indicators suggest that Bitcoin's economic role has surpassed that of direct trading alone. However, ownership, liquidity, and collateral uses measure different aspects of the market and should not be combined into a single utilization rate figure. The key question is how these indicators will evolve over time, and whether changes in dormant supply, exchange balances, and financial deployments indicate a broader shift in the ways Bitcoin is being used.
Conclusion: The supply of Bitcoin and its economic utilization tell different stories.
The supply structure of Bitcoin indicates that, in addition to a large base of long-term holders, the pool of truly liquid supply is relatively small, yet its financial uses are expanding. Approximately 6.84 million BTC coins have not been transferred for at least five years, and in the measured liquidity datasets, about 13.41 million BTC coins are classified as illiquid.
Institutional exposures provide another dimension to the picture. The US spot Bitcoin ETF market holds approximately 1.29 million BTC, corporate treasuries hold Bitcoin as a reserve asset, and the credit market uses BTC as collateral. These figures represent different aspects of the ecosystem and should not be viewed as independent and non-overlapping parts of the total supply.
The key finding of the report is that the money supply of Bitcoin does not equal the amount that can be used for transactions at any time or that is actively utilized in financial markets. The dormant supply indicator reveals holding behavior, exchange balances help to assess the inventory on trading platforms, while institutional holdings and collateral data show how BTC is held or deployed. Continuously tracking these indicators helps to determine whether Bitcoin is becoming more liquid, transferred more frequently, or gaining broader use in financial applications.