Jiangbolong expects its net profit attributable to the parent company to range from 14 billion to 14.9 billion yuan in the first three quarters of 2026, a year-on-year increase of 1864.55% to 1990.84%.
The Block
51m ago
Ai Focus
Jiangbolong releases performance forecast for the first three quarters of 2026, expecting operating revenue of 38 to 40 billion yuan, net profit attributable to the parent company of 14 to 14.9 billion yuan, and non-recurring net profit of 13.8 to 14.8 billion yuan; the company stated that the cash flow from operations in the third quarter was positive, and the asset-liability ratio is below 50%, however, the actual performance data will be subject to the official third-quarter report to come.
Helpful
No.Help

IT News from October 15th: Jiangbolong has released its performance forecast report for the third quarter of 2026 (January to September 2026) today:

Total operating revenue: 38 billion to 40 billion yuan, a year-on-year increase of 127.08% to 139.03%
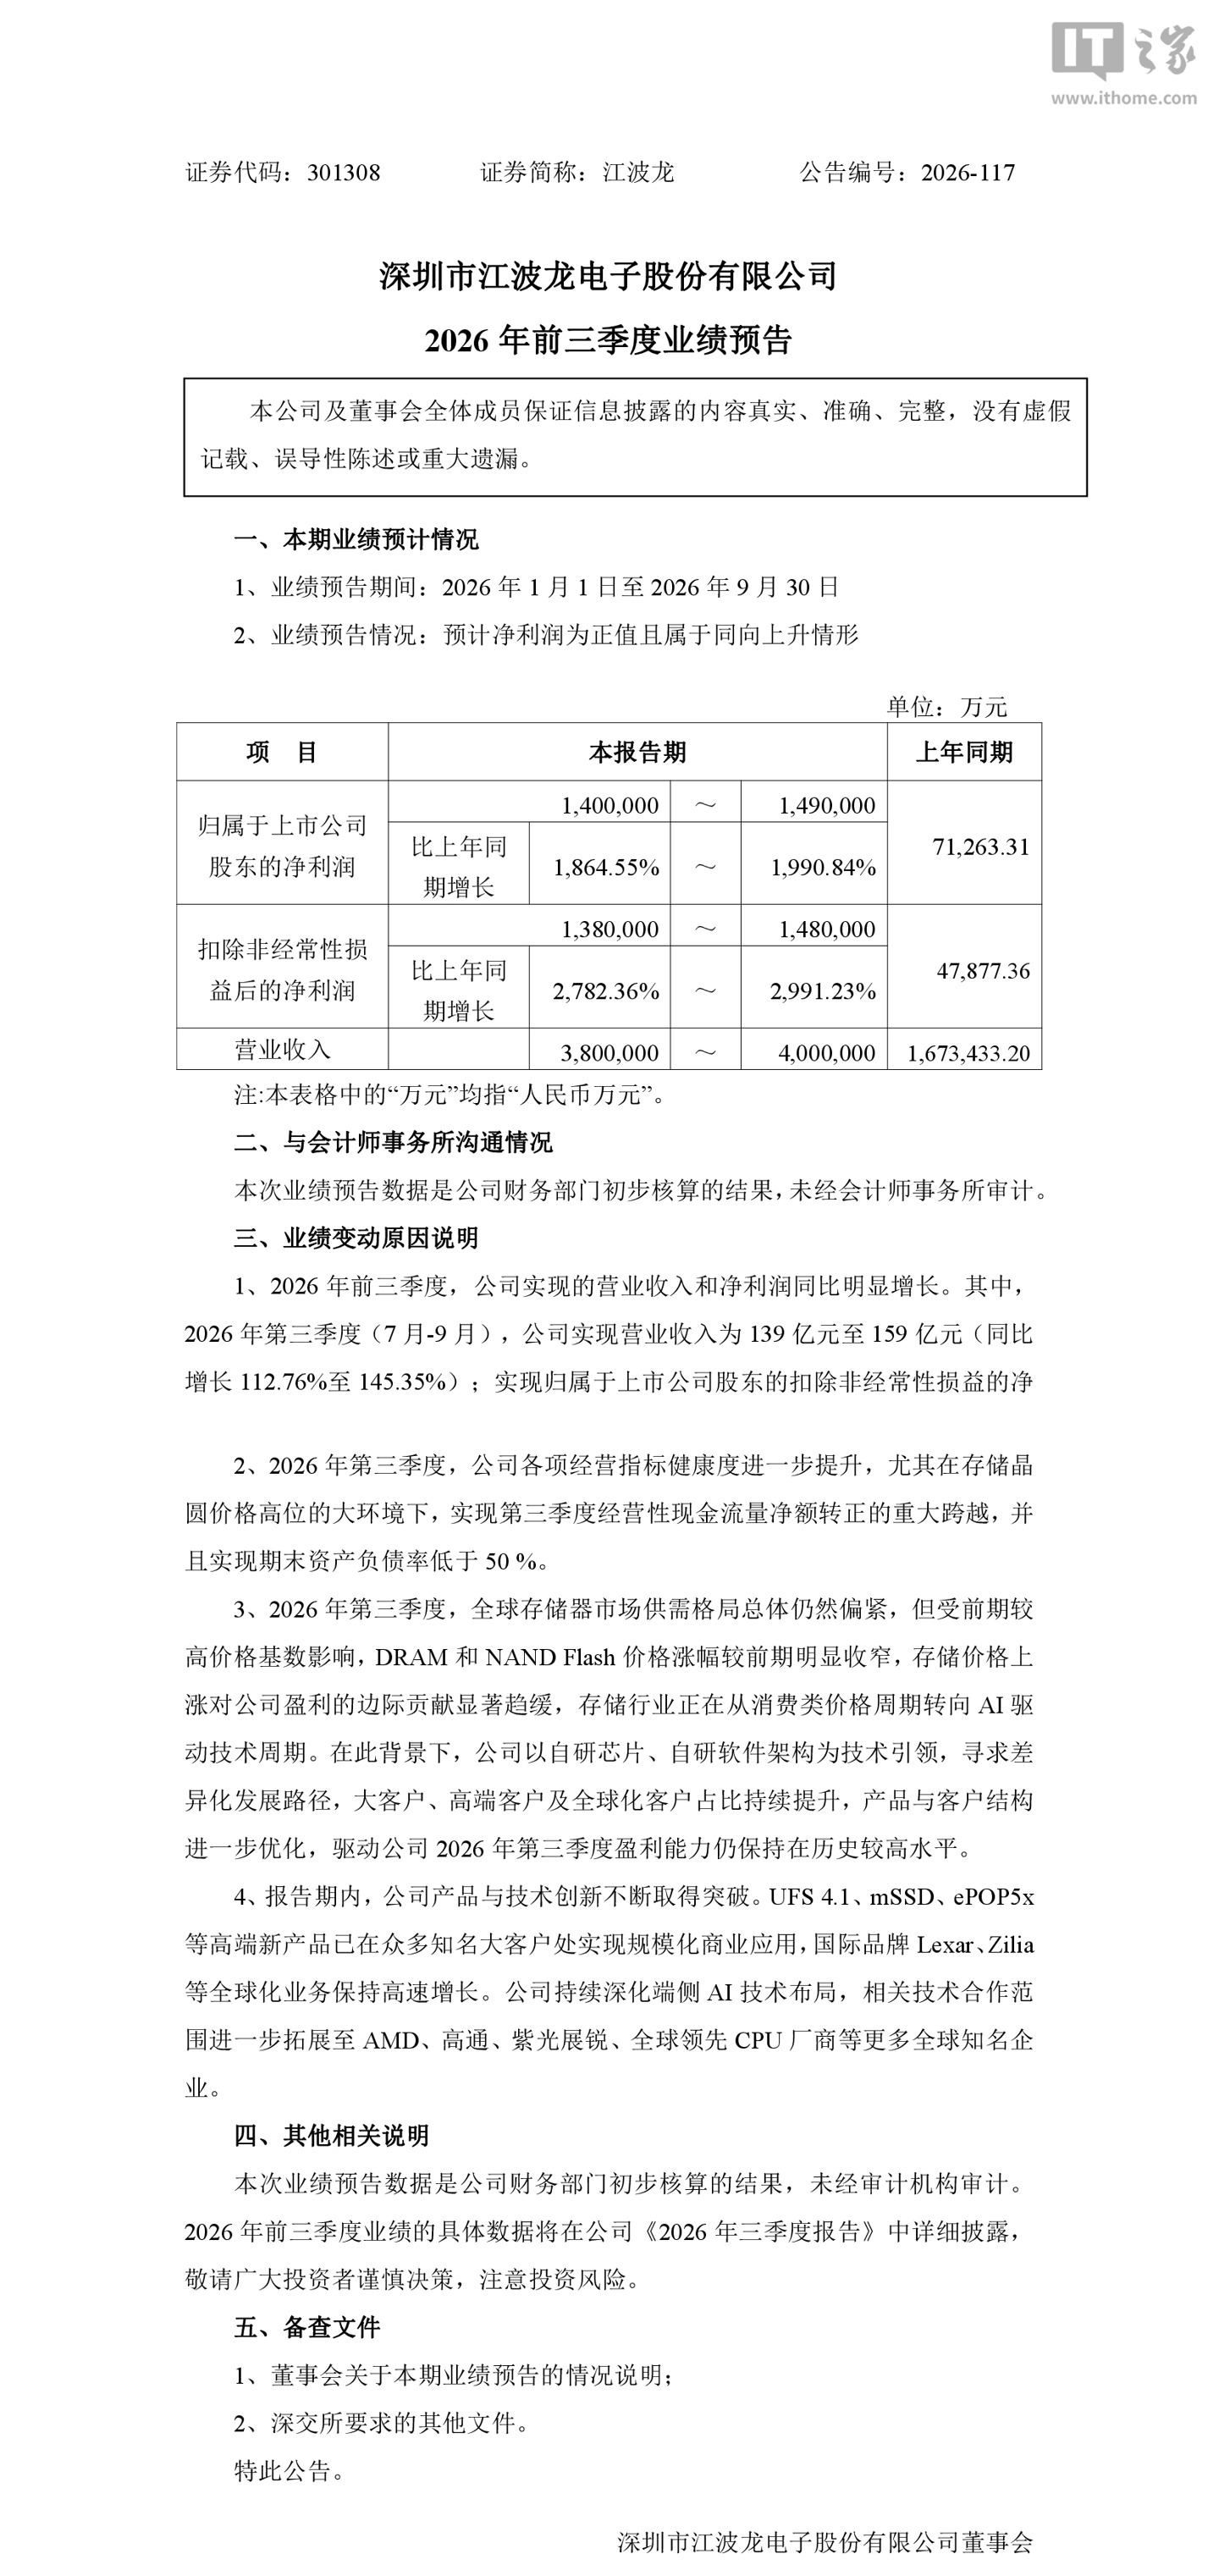
Net profit attributable to the parent company: 14 billion yuan to 14.9 billion yuan, a year-on-year increase of 1864.55% to 1990.84%

Non-recurring net profit: 13.8 billion to 14.8 billion yuan, a year-on-year increase of 2782.36% to 2991.23%

Debt-to-asset ratio: 50%

IT's performance forecast for this time has significantly exceeded the market's consensus expectations, with both net profit attributable to the parent company and revenue growth rates standing out.

Jiangbolong is a domestic enterprise dedicated to the research, development, production, and sales of consumer-grade, industrial-grade, and automotive-grade storage products. Its products cover multiple high-end storage fields such as UFS, SSD, and ePOP.

In the first three quarters of 2026, the company expects to achieve operating revenues of 38 billion to 40 billion yuan, compared to 16.734 billion yuan in the same period last year; it aims to achieve net profits attributable to shareholders of the listed company of 14 billion to 14.9 billion yuan, a year-on-year increase of 1864.55% to 1990.84%, whereas the net profit in the same period last year was 713 million yuan; after deducting non-recurring gains and losses, the net profit is expected to be 13.8 billion to 14.8 billion yuan, a year-on-year increase of 2782.36% to 2991.23%, compared to 479 million yuan for the same period last year.

On a quarterly basis, in the third quarter of 2026, the company achieved operating revenue of 13.9 billion to 15.9 billion yuan, representing a year-on-year increase of 112.76% to 145.35%; net profit after deducting non-recurring gains and losses was 3.753 billion to 4.753 billion yuan, with a year-on-year increase of 740.33% to 964.26%, maintaining a historically high level of profitability.

In the third quarter, the company achieved a net positive operating cash flow, and the asset-liability ratio at the end of the period was below 50%, further indicating an improved level of operational health.

The company stated that the overall supply and demand situation in the global memory market is tight. However, due to the higher price base from earlier periods, the price increases for DRAM and NAND Flash have narrowed significantly compared to before. The marginal contribution of rising memory prices to profits has slowed down, and the industry is transitioning from a consumer-oriented price cycle to a technology-driven cycle driven by AI.

The company stated that it leads with its own-developed chips and software architecture, pursuing a differentiated development path. The proportion of major customers, high-end customers, and global customers continues to increase, and the product and customer structure has been further optimized.

The company stated that with continuous breakthroughs in technological innovation, high-end new products such as UFS, mSSD, and ePOP5x have been commercially adopted on a large scale by well-known customers, and its international business continues to grow at a rapid pace. On the client-side, the technical cooperation with AI has further expanded to include globally renowned companies such as AMD and Qualcomm, opening up additional room for growth.

Tip
$0
Like
0
Save
0
Views 20
HKWDB reminds readers to view blockchain rationally, stay aware of risks, and beware of virtual token issuance and speculation. All content on this site represents market information or related viewpoints only and does not constitute any form of investment advice. If you find sensitive content, please click“Report”,and we will handle it promptly。
Submit
Comment 0
Hot
Latest
No comments yet. Be the first!
Related
Storage chip stocks suffer heavy losses; concerns over Chinese competition and oversupply by 2029 rise
Storage chip stocks tumbled significantly this week, with the market concerned about intensified competition from China and a potential oversupply in the coming years. Analysts and industry insiders are skeptical about whether the expansion of CXMT's production capacity will truly increase supply, but discussions regarding an oversupply of RAM in 2029 continue to simmer.
CNBC
·2026-10-15 20:26:22
0
Solana Mobile Launches Its First Hardware Expansion Partner: Ledger Atom
Solana Mobile announces its first hardware expansion partner as Ledger. Ledger will launch new devices Ledger Atom pre-installed with Seeker applications, and the two parties will collaborate to integrate Solana and dApp stores and wallets into this new flagship device.
SolanaFloor
·2026-10-15 20:16:29
7
KB Home Launches New Community in St. Augustine, Florida: Sebastian Oaks Starting from Just $300,000
KB Home announces the official opening of its new residential community Sebastian Oaks located in St. Augustine, Florida. The starting price of properties ranges from $300,000, offering single-family homes with one to two floors and up to 5 bedrooms and 3 bathrooms. The community is close to beaches, schools, and major traffic arteries, and the sales center as well as model homes are now open for visits.
PR Newswire
·2026-10-15 20:16:26
8
Amazon Launches New Bee "Personal AI" Device That Can Monitor Conversations
Amazon released two new Bee listening devices on Thursday, including a wearable device and a recorder the size of a credit card, continuing to strengthen its presence in the AI hardware market. The new products include the Bee Frontier priced at $75 and the Bee Eclipse priced at $100; the latter can be magnetically attached to the back of a smartphone. Amazon also stated that the devices will continue to record audio, but will not store it.
CNBC
·2026-10-15 20:16:23
9
Dell's stock price tumbles 11%: Is the AI server boom losing momentum?
Despite the strong demand for AI servers, investors are re-evaluating valuations and questioning whether the company's expenditures can support the growth expectations already factored into the hardware company's stock price. Barclays has downgraded Dell's rating from 'overweight' to 'neutral' and reduced its target price from $603 to $574, stating that the company's AI expenditures may not accelerate fast enough. Dell also disclosed $60.9 billion in AI orders, $16.4 billion in AI optimized server revenue, and a record $95 billion in backlogged orders, and raised its full-year revenue forecast for fiscal year 2027 to $192 billion.
Coinpedia
·2026-10-15 20:05:46
16
View More