Meta Platforms ( NASDAQ : META ) and Tesla ( NASDAQ : TSLA ) have just released their latest quarterly financial reports, but investors seem to be more excited about the performance of this social media giant than that of this electric vehicle manufacturer. In after-hours trading on Wednesday, the stock price of Meta rose by about 3%, while Tesla fell by about 2%, despite the latter achieving encouraging results in several highly watched areas.
The reaction to Tesla has been rather lukewarm, conveying another layer of meaning, especially against the backdrop of encouraging progress in its autonomous driving business. The company reported a gross margin higher than expected, with positive free cash flow, and subscriptions for full autonomous driving (FSD) continue to grow. However, these achievements have not convinced investors that Tesla is on the verge of a sustained recovery in profitability.
Meta announced third-quarter revenue of $64.6 billion, a year-on-year increase of 26%, exceeding Wall Street's forecast of $63.32 billion. Adjusted earnings per share were $7.40, surpassing the expected $6.80; after accounting for a significant legal expense, the reported earnings per share were $3.83.
Reality Labs continued to report losses this quarter, with operating losses amounting to $4.13 billion. Nevertheless, Meta has projected revenue for the fourth quarter to be between $73 billion and $76 billion, indicating that its advertising growth momentum may continue until the end of the year.
Meanwhile, CEO Mark Zuckerberg is accelerating the company's pursuit of individual superintelligence and incorporating Muse and Muse Wonder into its ongoing artificial intelligence initiatives. These projects require substantial investment, and the company currently expects annual capital expenditures to reach between $135 billion and $145 billion.
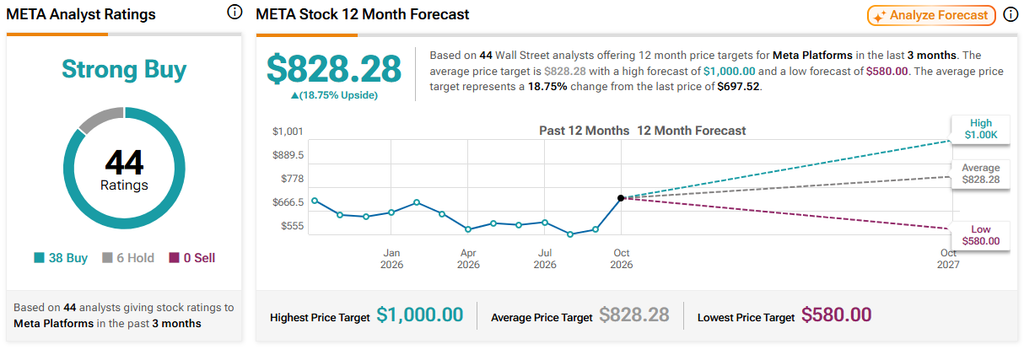
The scale of this financial investment is considerable, but Wall Street seems to believe that Meta has the capability to undertake this costly technological expansion. The stock currently holds a unanimous rating of “strong buy,” based on 38 buy recommendations and 6 hold recommendations. Its 12-month average target price is $828.28, which implies a potential increase of about 19% from Wednesday’s closing price. (See META stock price forecast)
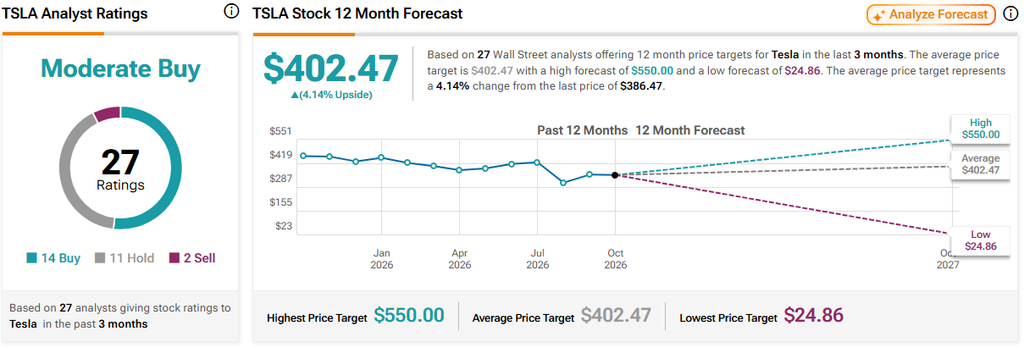
Tesla Gross profit margin exceeds expectations, but profitability remains a concern
Tesla announced third-quarter revenue of $28.1 billion, which is basically the same as the same period last year and in line with Wall Street's expectations. Adjusted earnings per share were $0.48, higher than the market consensus of $0.45, but lower than $0.50 in the same period last year.
The company's gross margin rose to 19.6%, exceeding the expected 17.8%; the profitability of its automotive business was 18.1%, also surpassing expectations. Following a negative figure in the second quarter, free cash flow rebounded to $1.53 billion and turned positive again.
However, Tesla's operating profit margin dropped from 5.8% in the same period last year to 2.6%, indicating that despite the improvement in gross profit margin, challenges still exist.
This automobile manufacturer delivered 486,532 vehicles this quarter, while the number of active FSD subscriptions increased by 67% to reach 1.74 million. Tesla held $45.5 billion in cash at the end of September, providing financial flexibility for its autonomous driving and robotics projects.
In addition to traditional automobile sales, Elon Musk's company is still investing in technologies that may ultimately change its revenue structure. The growing adoption rate of FSD provides positive evidence of customer demand, but the financial contribution brought by autonomous driving services remains relatively limited.
Disclaimer and Disclosure
Report an issue
Meta Platforms News More