After the U.S. midterms, Bitcoin: Can a rebound withstand the ETF sell-off?
Bitcoin rebounded after a night of intense volatility during the election, but the outflow of funds actually began before Americans finished voting. Whether the next phase of the rebound can continue will depend on whether demand returns after investors re-evaluate the risks associated with Congress, interest rates, and exchanges.
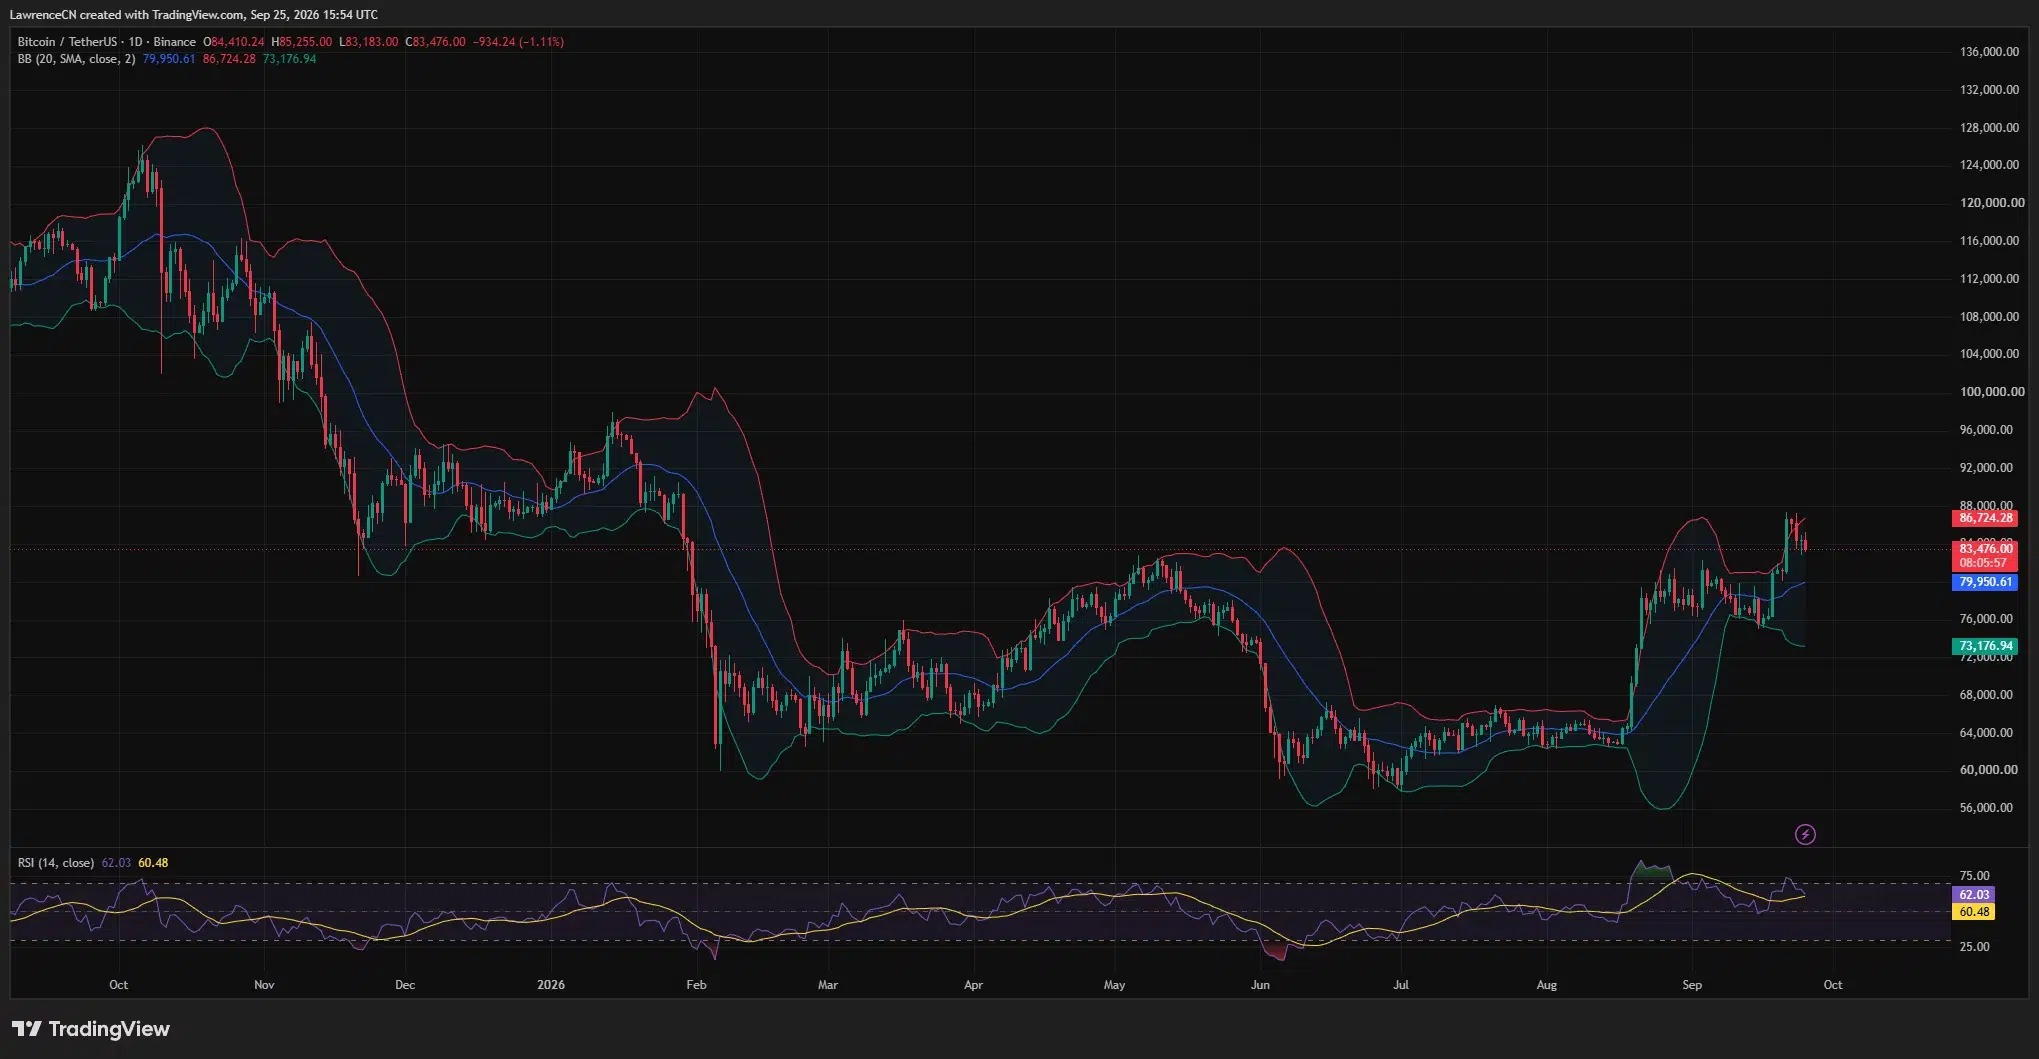
- After dropping to around $75,700 during the trading session on November 4th, Bitcoin rebounded to nearly $77,900.
- Summary data from Farside shows that on October 30th, there was a net outflow of $643.2 million in spot Bitcoin ETF from the United States.
- On November 2, another $398.6 million flowed out of these funds, and on November 3, an additional $115.6 million was withdrawn.
- On October 28, the Federal Reserve maintained its policy interest rate range at 3.75% to 4%.
- The U.S. employment report for October is scheduled to be released on November 6th at 8:30 a.m. Eastern Time.
As the results of the U.S. mid-term elections came in, Bitcoin rebounded from around $75,700 to around $78,000; at the same time, ETF experienced capital outflows for the third consecutive trading day, putting this rebound in direct confrontation with institutional selling pressure.
According to the price page of crypto.news, on November 4th, Bitcoin was trading at around $77,851, with a 24-hour range of approximately $75,695 to $77,990.
The Associated Press reports that the Democratic Party has won control of both chambers of Congress. For investors, this means that the political landscape during President Trump's remaining term will change, although the election results themselves will not alter the existing financial laws.
The decline of Bitcoin did not begin only when the election results were announced. US-listed spot funds had already experienced significant outflows of capital, and at the same time, the market was still dealing with a security vulnerability that occurred on October 29th with Binance.
Bitcoin was already under selling pressure before election night.
As previously reported by crypto.news, on November 3rd, Bitcoin fell below $77,000 against the backdrop of fund outflows, leveraged liquidations, and a weakening in tech stocks. Therefore, the entire decline cannot be attributed to the election results alone.
The market can respond to multiple developments simultaneously. Investors concerned about policies may sell, while other holders might reduce their risk after exchange events, and traders could also close out leveraged positions.
The quotes record the points where these orders intersect, and they do not include the reasons of each buyer or seller; moreover, the titles written afterwards cannot reconstruct these reasons solely based on the charts.
However, the election still provides new information. Changes in control of Congress will affect the leadership of committees, legislation, and the expectations for negotiations with the White House.
The real question is how much of this type of information investors have already factored into the prices. A result that is widely anticipated may not have a lasting impact; whereas an unexpected outcome could force rapid adjustments to positions.
Therefore, a rebound may occur after the initial decline, without the need for a reversal in political news. The selling pressure may have already been exhausted, bears may cover their positions, or other investors may find lower prices more attractive.
The range on November 4th illustrates how rapid this change is. From approximately $75,695 to $77,990, the difference is about $2,295, which is equivalent to around 3% of the lower price.
However, this intraday range does not equate to a daily increase of 3%. Daily returns depend on the time points being compared, while the range records the highest and lowest values within the selected time window.
Therefore, readers who track different priced services may see varying percentages of increase or decrease, and this does not necessarily mean that one of them is incorrect. The trading venues, methods of aggregation, and scrolling measurement windows can all differ.
If one wants to observe the subsequent trend, a better starting point is a clear date and a well-defined observation period. The real-time Bitcoin page provides continuous quotes, whereas the numbers mentioned in this article describe a research snapshot from November 4th.
A total of over $1.15 billion flowed out on three ETF trading days.
The daily capital flow table for Farside Investors shows that on October 30th there was a net outflow of 643.2 million US dollars, on November 2nd an outflow of 398.6 million US dollars, and on November 3rd an outflow of 115.6 million US dollars. Adding these rounded daily figures together, the total amounts to 1.1574 billion US dollars.
This calculation covers three trading days that are separated by weekends, not three consecutive natural days; without further clarification, it should not be directly combined with data from another institution that uses a different rounding method.
The speed of capital outflows has significantly slowed down. On November 3rd, the net outflow was approximately 82% less than on October 30th. The calculation is done by subtracting $115.6 million from $643.2 million and then dividing the result by $643.2 million.
A slowdown in outflows can alleviate some pressure, but this does not equate to an inflow of funds, nor does it guarantee that the situation will turn positive on the next trading day.
This distinction is very important for judging a rebound. Even if the fund is still losing value, as long as other buying orders absorb the supply or the number of selling orders decreases, Bitcoin can still recover.
The data for these three days represents a preliminary summary of the daily data listed, measuring the net flow within the US products being tracked, rather than changes in Bitcoin holdings of all institutions globally.
The data for Farside is rounded to one decimal place in millions of US dollars. Due to differences in precision, reporting methods, or subsequent revisions, other services may provide slightly different totals.
Another issue is the relationship between fund capital flows and spot transactions. Net redemptions describe the changes in a fund's capital or shares through the subscription and redemption mechanism, but they do not provide a timestamp list for each underlying Bitcoin transaction.
However, this total amount still provides a concrete measure of the demand prospects. If funds continue to flow out, it means that to maintain higher prices, other buyers will need to bear more of the burden.
If it turns back to net subscriptions, the situation will change. Several consecutive trading days of positive inflows are more indicative than a single positive value, especially against the backdrop of previous large cumulative outflows.
Emission party's explanation on data segmentation; the overall data needs to be understood in context.
The capital flow records distinguish the overall net outflow, which does not mean that each fund is selling simultaneously. Even if the market as a whole is in a negative trend, there may still be some products that attract capital inflows at the same time.
This situation occurs when holders switch between different providers, or when different groups of investors make different decisions. Lower fees, distribution relationships, and combination authorizations can all affect which product the funds will ultimately flow to.
An investor who sells one fund and buys another may actually still maintain an almost identical Bitcoin exposure. Even if the net result by category does not change much, the gross trading volume can still be quite substantial.
The overall data is useful precisely because it netifies these flows; and the detailed rules set by the issuers help to explain whether the negative values are concentrated in a few products or are spread across the entire group.
However, neither of these two measures is able to identify the intentions of each individual holder. Fund holders may include institutions, advisors, individuals, and trading companies, and their time spans can vary greatly.
Therefore, it is more accurate to say that there has been a net outflow of US spot Bitcoin ETF rather than to generalize it as "institutional outflows." The latter refers to the actual instrument that is being measured.
Even without any capital outflows, fund assets may decrease due to the decline in Bitcoin; conversely, during periods of net redemptions, assets may increase as long as the remaining positions appreciate sufficiently.
The trading volume of fund shares is another independent indicator. When buyers purchase existing shares from sellers, it leads to transactions on the exchange, but it does not necessarily result in the creation of new fund shares or new underlying positions.
Therefore, the price outlook should be assessed based on net subscriptions, underlying positions, and asset value separately, rather than treating all three as investor cash flows. Otherwise, it would lead to misleading judgments about demand.
Time points are also equally important. ETF data is usually compiled at the end of the trading session in the United States, whereas tokens continue to trade across time zones and on weekends.
The rebound during the Asian session may begin before the next release of U.S. fund results. It will be easier to assess its sustainability after U.S. investors have completed a full trading session.
The Democratic Party first changed expectations regarding control, and then altered the law.
The election results have created a new political environment for crypto policies, but the majority of seats in Congress itself do not pertain to rules regarding exchanges, custody, or Bitcoin holdings. Further legislative changes are still required through additional procedures.
The work pace of the new Congress is different from that on election night. Existing officials and institutions will continue to operate until the new members take office.
The committee leadership will influence which proposals will receive hearings, as well as the rigor with which regulatory agencies and companies will be scrutinized. These decisions may affect expectations even before any legal changes are made.
To pass legislation, consensus must be reached through constitutional procedures. The majority in the House of Representatives, the majority in the Senate, and the President may have different priorities, and ultimately, it will depend on negotiations to determine which provisions will become law.
The procedural requirements of the U.S. Senate may also add an additional hurdle to controversial bills. A narrow electoral victory should not be seen as an automatic guarantee for the passage of the entire policy package.
Encryption policies do not entirely align with party labels. Even within the same party, different members may hold varying positions regarding proposals concerning stablecoins, securities markets, bank access, and illegal finance.
If we simply translate the election results into a unified judgment for the entire crypto industry, the prospects of Bitcoin may overlook these differences. Measures that affect one company or one business model may not necessarily have the same impact on the assets themselves.
Even while waiting for details, investors can still price in uncertainty. If the perceived risk of restrictive measures increases, investors' demands for returns on holding that asset may also rise, even before such restrictions are legally mandated.
Conversely, if negotiations make future rules clearer and reduce uncertainty, it may also lead to an increase in participation, even if the final framework includes obligations that companies would not have wished to undertake in the first place.
Neither of these two channels will provide a fixed target price for Bitcoin. The impact depends on the content of the policies, the probability assigned to it by investors, and the performance of other markets at that time.
The next batch of useful policy evidence will come from the named leaders, committee agendas, and the actual legislative texts. The election night commentary is just a starting point and not the final operational framework.
Interest rates remain another source of pressure.
On October 28, the Federal Reserve maintained its target range at 3.75% to 4%. Its policy statement stated that inflation was still on the high side, and two officials advocated for a 25-basis-point interest rate hike.
This time, the decision is to hold our ground rather than cut interest rates. The opposition advocates for stricter policies, which is important when interpreting the claim that "the monetary environment is already being relaxed."
The results of parliamentary elections cannot replace the policy process of the central bank. Fiscal decisions will affect economic prospects, but the Federal Reserve will still assess employment, inflation, and financial conditions.
For investors, interest rates affect the returns that cash and government bonds can provide. Bitcoin does not pay the agreed-upon interest, so changes in the returns of alternative assets will influence investment portfolio decisions.
However, this relationship is not mechanical. Even if interest rates are high, Bitcoin may still rise as long as other sources of demand increase; conversely, during periods of expected easing, if investors are concerned about economic deterioration, Bitcoin may fall.
The yield on government bonds itself consists of multiple components, including expectations for short-term policy interest rates and the compensation required for holding long-term bonds. A decline in long-term yields does not alone indicate the specific reason for it.
The US dollar also introduces another layer of uncertainty. A weakening of the US dollar will change the comparison benchmark for international buyers, but exchange rate fluctuations do not guarantee that funds will necessarily flow into Bitcoin.
Previously, in October when the interest rate decision was reported, Bitcoin was around $80,800. The current price is even lower, but this period has coincided with exchange vulnerabilities, capital outflows, elections, as well as monetary policy announcements.
If we attribute all the differences to the Federal Reserve, we would be making the same mistake as attributing them all to the mid-term elections. A series of consecutive events can change prices, but it is not possible to clearly separate the contribution of each individual event.
Employment data provides investors with several indicators that may point in different directions. The technical notes from the U.S. Bureau of Labor Statistics distinguish between household surveys and institutional surveys: the unemployment rate comes from the former, while non-agricultural employment data comes from the latter.
These two surveys measure different groups of people and concepts. If a person has more than one job, their performance in terms of 'number of employed people' and 'non-agricultural employment positions' may vary, therefore the two headline figures may not change in sync.
The correction values will also change the starting point. New month's employment growth may be announced simultaneously with the corrections from previous months, thereby affecting the cumulative employment picture on which investors rely.
For example, if 100,000 new jobs are created and at the same time 100,000 jobs are reduced from the total of previous months, then the overall employment level will not be higher than the baseline reported before, plus zero. What appears to be positive news may be accompanied by less optimistic cumulative changes.
This example is merely an arithmetic illustration and not a prediction for the Friday report. It illustrates why focusing only on the first number may lead to missing other information that is released at the same time.
Wage increases lead to another issue, namely labor costs and purchasing power. Investors evaluating inflation and policies may react differently to the same employment figures due to varying wage data accompanying them.
A weaker report is not necessarily favorable for Bitcoin. Lower expected interest rates may support a risk appetite, but a deteriorating economic outlook could also lead investors to reduce their exposure to risky assets at the same time.
The reaction of yields and the US dollar can show how the market interprets this data. The trading of Bitcoin itself will reveal whether the new buying orders are sufficient to offset the selling orders that are already active through funds and exchanges.
It is quite useful to compare the first minute after the announcement with the entire trading period, as orders placed immediately after the data release may drive a market movement that later reverses. Continuous reactions provide a better indication of the balance of power between buyers and sellers than the initial price fluctuations.
Therefore, the results of the mid-term elections and the employment report correspond to different timelines of information. Even if there are no changes in the political landscape, investors who bet on politics will still face a set of new economic data before the end of this week.
A more useful way to judge the outlook is to observe whether interest rate expectations, yields, and the direction of the US dollar are in line with the buying trend of Bitcoin, or whether they cancel each other out. If these observations are consistent, it can support a certain scenario, but it does not prove a single causal explanation.
Exchange funds can be transferred out without selling tokens.
The security incident involving Binance remains part of the market context. The exchange stated that approximately $6.3 billion in assets were affected and pledged to bear the financial consequences.
On November 2nd, the reserve verification covered 10 different cryptocurrencies, using a snapshot from October 31st. Another snapshot that covers more assets was originally scheduled to be released on November 4th.
These disclosures indicate the asset-backed situation at a certain point in time and do not individually describe whether each customer subsequently decided to place their assets elsewhere or whether they chose to sell them.
Withdrawing funds from an exchange can be transferred to a personal wallet, a custodian institution, or another trading platform. It may reduce the assets held by a particular company, but it does not decrease investors' exposure to Bitcoin.
Selling is another matter. The holder hands over the asset to the buyer, and the transaction price depends on the bid available at the time of order execution.
If investors withdraw their coins first and then sell them elsewhere, there could certainly be a connection between the two actions; however, the act of withdrawing coins alone does not prove that the second step has taken place. To interpret every outflow from a transaction as either bullish hoarding or bearish selling is to attribute motives to that transfer that have not been revealed.
A similar distinction is also needed for reserve data. It describes the quantity held in identified wallets, or the quantity reported by operators, rather than a direct measure of how confident customers are about their transactions tomorrow.
Investors can hold products that are fully backed by assets and at the same time choose to change their custodians; they can also remain on a certain platform, but reduce their exposure to price risks.
During periods of operational interruptions, market-making activities may also change. When transfers slow down, or when the availability varies across different platforms, it may become more difficult for traders to transfer their holdings to where they are needed.
The resulting price difference can affect the execution of transactions, but it does not mean that there has been any change to the underlying assets themselves. Therefore, restoring the transfer channel and withdrawal function is closely related to the smooth operation of the market.
Regarding the prospects after the election, both the recovery of exchanges and policy expectations should be included within the same reporting framework, but they should not be confused as one explanation. Each has its own independent observable progress and timeline.
Short covering may drive a rebound before investment demand returns.
Short sellers buying back Bitcoin will create demand during a rebound. This buying could be forced by margin requirements, or it could be an active move to lock in profits after a decline.
In either case, traders are not required to become long-term bulls. Once the shorts close their positions, this portion of buying orders will cease, unless participants re-establish a positive position.
Leverage will amplify this effect. A small change in the underlying asset may correspond to a larger change in the equity on which the borrowed position relies.
In a simplified 10x leverage trade, a 1% change in the underlying asset roughly corresponds to a 10% change in initial equity, without considering fees or margin requirements. The actual forced liquidation level depends on the trading venue, collateral, and other account conditions.
Therefore, a rapid rebound may force more short sellers to cover their positions, while another decline could compel leveraged long sellers to sell. These feedback effects will cause greater market volatility, but they will not provide new fundamental reasons for each trade.
Unclosed contracts help to describe the number of derivative contracts that are still in existence. A decrease in unclosed contracts during a rebound may be consistent with the closing of positions; an increase in unclosed contracts may indicate that new contracts are being established.
However, on the other side of each contract, there is also an counterparty, so the total amount cannot be interpreted as the scale of new funds betting on a rise in Bitcoin prices.
The funding rate describes the costs or payments between the two parties of a perpetual contract. A positive funding rate does not guarantee that prices will rise, and a negative funding rate does not guarantee that short positions will be squeezed.
A more useful comparison is to look at the position cost in conjunction with spot market activity. A rebound supported by executable spot buy orders has a different foundation from one that is mainly driven by forced liquidations.
No single indicator can resolve this difference on its own. By matching observation periods and comparing multiple trading venues, the risk of mistaking local market events for overall Bitcoin transaction changes can be reduced.
The next trading session in the U.S. could provide another piece of evidence. Whether fund subscriptions or redemptions show that investors using these products are increasing or decreasing demand elsewhere will become apparent.
Hedged institutional transactions can be unwound without new political viewpoints.
Institutions holding bitcoin positions can hedge some or all of their price risks through futures. Therefore, selling spot positions may merely be one component of a portfolio trading adjustment, rather than an independent judgment regarding the long-term value of the assets.
The difference between the futures price and the spot price is called the basis. When futures are higher than the spot price, traders can attempt to buy the asset and sell the futures, in order to capture the price difference as the contract approaches settlement.
The explanation of the basis index by CF Benchmarks indicates that spot exposures and systematic futures hedging can be combined into a strategy. This approach utilizes CME futures data and adjusts the hedging according to maturity structure.
The existence of this strategy does not necessarily prove that it led to the recent outflow of funds from ETF; it merely indicates that the bitcoin exposures held by the fund and those of unhedged investors are not necessarily identical.
Assuming the spot price is $78,000 and the futures price for expiration in 90 days is $78,780, then the gross difference is $780, which is equivalent to 1% of the spot purchase price.
When annualized by dividing 365 by 90, it is approximately 4.1%. This calculation does not include fees, financing, margin requirements, execution differences, or the risk of positions not being able to be maintained as expected.
If traders pay a higher cost to finance this set of combined positions than the return they receive, then their motivation will differ from that of investors who already hold cash. The spread mentioned in the title does not equate to a guaranteed net profit.
If the price difference narrows, a trade that was originally attractive may become less profitable. Closing a position may involve selling the physical commodity and buying back the futures short position, thereby reducing both sides of the position at the same time.
Even if traders do not form new bearish views on Bitcoin, spot sales may still appear in the demand data; at the same time, futures purchases will unwind hedging, which is not visible just by looking at the ETF trades.
The cryptocurrency futures guidelines for CME list the specific settlement and operating conditions for each contract. These details determine the tools that will be used; perpetual contracts on crypto exchanges are not equivalent to every futures contract that has an expiration date.
Different tools have different cash flow rhythms. Sustainable positions may continuously generate funding rates, while contracts with expiration dates have a time limit for expiration, and the basis will change over time and with market conditions.
Therefore, in the assessment of the post-election prospects, it is reasonable to consider futures and fund flows together. If the spot exposure decreases, and at the same time the hedging of shorts also reduces, then this represents a different situation compared to investors selling directly without any hedging.
Publicly aggregated data may not necessarily reveal the pairing details of each combination. Fund flow tables only show what occurs within the products they track, while derivatives data describe the position situations at the relevant trading venues.
These two types of data can be compared with each other within the same time period, but it is not possible to assume that each contract corresponds to a known ETF holder. Nevertheless, their limitations are still significant when attributing market trends to electoral sentiment.
The sustainability of truly returning, unhedged investment demand will differ from that of short-term arbitrage adjustments. This distinction will affect whether the buying pressure can continue after the price gap is filled.
Institutions can use both methods simultaneously, and their relative scales may also vary. A single label such as 'institutional selling' cannot encompass all the transactions behind the total negative daily fund amount.
There are measurable conditions for returning to the $80,000 level.
Referring to $77,851 as a benchmark, a return to $80,000 would require a rise of about 2.8%; whereas a drop to around $75,000 would correspond to a decrease of approximately 3.7%.
Compared to the historical volatility of that asset, these distances are not significant, but they do not indicate an equal probability. Which type of transaction actually occurs depends on the available buy and sell orders, as well as the flow of news.
The market situation requires buyers to maintain prices above the recent range, while at the same time, the outflow of fund capital should further slow down or even turn positive. If there is continuous demand support throughout the entire US trading session, it would indicate a more solid trend than just a short-term rebound overnight.
If the trend above $80,000 mainly relies on and quickly ends with short covering, then this level remains fragile. If transactions can be repeatedly made above that price level, and there is greater participation from spot traders, it will be more conducive to the formation of a new range.
These distances can be listed out, but one should not pretend that they are probabilities. Each of the following results starts from $77,851, and assumes there are no fees or leverage involved.
The calculation method in the table is to divide the price by the starting reference price and then subtract 1. This does not mean that these target levels are technical support or resistance, nor does it imply that a fixed amount of investor funds will necessarily drive these changes.
For a hypothetical 0.1 BTC unhedged position, for every $1,000 change in the price of Bitcoin, the gross value of the position changes by $100. The equity changes in leveraged accounts may vary, and the position could be liquidated before a final rebound occurs.
A neutral scenario would see Bitcoin fluctuate between lows on election night and a rebound range. Such trading activity indicates that investors are still looking for counterparts within the current range.
A downward market scenario would mean that selling pressure once again breaks through the $75,700 level, and it will not be possible to regain that range. By then, the $75,000 figure will become a reference point that needs attention, rather than a confirmed bottom.
If the following observations occur, the bearish arguments will be weakened: sustained net inflows of ETF, a decrease in financing costs for positions, and spot buyers absorbing sellers without excessive leverage accumulation. Each of these points requires current evidence to support it.
There are also corresponding conditions under which the bullish arguments become invalid: continuous redemptions, deterioration of exchange liquidity, or if each rebound is met with selling back into the previous price range, all of which can reduce people's confidence in whether this round of rebound will continue.
The election results will still be part of these decisions, but the next batch of information planned for the market will include both economic data and political news. This week's economic calendar lists employment data as one of the important releases to come.
The U.S. Bureau of Labor Statistics' schedule for November indicates that the employment report for October will be released on November 6th at 8:30 a.m. Eastern Time, which is UTC time 13:30. This report includes data on non-farm employment, unemployment rates, and wages, and investors will also assess the revised figures from previous months at the same time.
What needs attention?
- ETF Trading Day Results: Comparing the latest data with a net outflow of $1.1574 billion on October 30th, November 2nd, and November 3rd.
- Recent trading range: Observing whether buyers can maintain the price above around $78,000, and whether the area around $75,700 will be tested again.
- Spot buying orders and position closing: Compare spot activities, open contracts, and funding rates over the same time period.
- Clear policy progress: Pay attention to the committee priorities and legislative texts that will be brought about by the upcoming formation of congressional leadership.
- Employment data for November 6: Pay attention to wages, unemployment rates, and revised figures, as well as the reaction of yields and the US dollar.
Frequently Asked Questions
Why does Bitcoin fluctuate around the time of the release of midterm election results?
The outcome has changed people's expectations regarding congressional control and policy, while the market was already facing uncertainties related to fund outflows and exchanges. Price charts alone cannot illustrate the contribution of each factor individually.
How much US spot Bitcoin ETF has flowed out in these three trading days?
The rounded total amount for Farside is approximately 1.1574 billion US dollars, covering the periods of October 30th, November 2nd, and November 3rd. This total includes trading days as well as weekends in between.
Is the outflow of funds slowing down?
Yes. The net outflow on November 3 was $115.6 million, which is approximately 82% less than the $643.2 million outflow on October 30. However, even though it is a smaller outflow, it is still considered a net outflow, not a net inflow.
Will the Democratic control of Congress automatically change encryption laws?
No. What the election results change is political control, while new legislative and regulatory actions must follow their respective procedures. It is the content and timing of the actual measures that determine their impact.
Did the Federal Reserve cut interest rates before the election?
No. On October 28th, the Federal Reserve maintained its interest rate range at 3.75% to 4%, with two officials advocating for a 25-basis-point interest rate hike. The statement continued to indicate that inflation remains high.
Does the departure of funds from an exchange mean that Bitcoin has been sold?
No. Tokens can be transferred to self-hosted accounts, another exchange, or an institutional custodian without constituting a sale. A simple transfer does not indicate any change in the holder's economic exposure.
What would make a rebound to $80,000 more convincing?
Sustained spot buying and a stable or improving ETF cash flow will support this trend, especially when leverage is kept under control. A brief break above an integer level is not as significant as maintaining that level consistently.
What economic data is next to be watched?
The U.S. employment report for October is scheduled to be released on November 6th at 8:30 a.m. Eastern Time. This article is for informational and educational purposes only and does not constitute investment advice.