The third-quarter reporting season for U.S. stocks has officially begun. The overall data appears impressive, but beneath the surface of prosperity, there are underlying issues: profits are highly concentrated, cost pressures are rising, and the market's tolerance for "surprises above expectations" has significantly decreased.
According to the latest report from Bank of America Securities, the market consensus for the third quarter expects earnings per share of the S&P 500 to increase by 27% year-over-year. Bank of America's own forecast is even higher at 32% (corresponding to $93.50 per share). Among the companies that reported earlier, 85% exceeded their earnings per share expectations, which is higher than the historical average of 71%. The macroeconomic backdrop remains generally favorable.
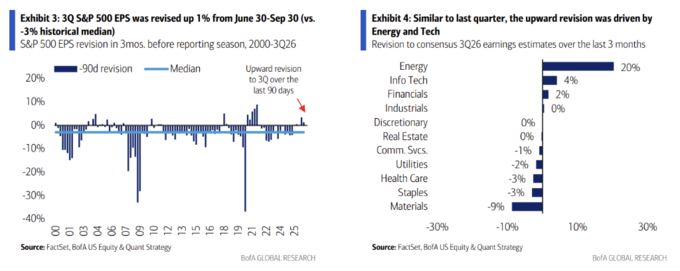
However, with large banks such as JPMorgan Chase, Goldman Sachs, Wells Fargo, and Citigroup making their appearances this week, the core contradiction of this earnings season is gradually coming to light: after experiencing significant outperforms in the past two quarters, "outperforming expectations" has itself become the new norm for the market. Can this still drive up stock prices?
BofA data shows that in the second quarter of 2026, 77% of the S&P 500 components exceeded earnings per share expectations – this is the highest success rate since 2021. However, the market's reaction has clearly become less vigorous: among companies that exceeded both earnings and revenue expectations, their outperformance relative to the S&P 500 the following day was only 0.7 percentage points, which is about half of the historical average of 1.4 percentage points; whereas when companies failed to meet expectations in both areas, their stock prices underperformed the index by an average of 3.3 percentage points the next day, which is slightly higher than the historical average penalty. This asymmetry clearly conveys a signal: the market is becoming more stingy with rewards for good news, while the punishment for bad news has not diminished at all.
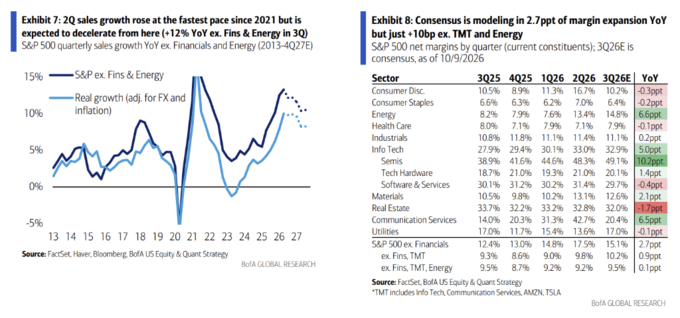
Bank of America warns that for investors, the real risks of this earnings season may not lie in the performance itself, but rather in three invisible killers: commodity costs eroding profits, doubts about the fulfillment of the AI narrative, and overly optimistic expectations for 2027.
Profit concentration reaches an all-time high, while the growth of mid-cap stocks has nearly come to a standstill.
On the surface, this quarter's financial reporting season is quite impressive: all 11 industries expected by consensus achieved positive growth, which is only the second time in history that has occurred. However, when the indices are broken down, the picture becomes quite different.
According to Goldman Sachs data, the top 10 stocks contributing to earnings in the S&P 500 are expected to contribute 68% of the total earnings growth for this quarter, a significant increase from 47% in the first quarter and 48% in the second quarter.
Among them, Micron Technology (Micron) contributed 19% to the index growth alone, and NVIDIA (Nvidia) contributed 15%. These two companies together accounted for 34% of the index's profit growth in the third quarter. The remaining contributors were Meta (7%), Google's parent company Alphabet (6%), and Broadcom (Broadcom, 5%). In addition, there were ExxonMobil, Chevron, and Marathon Petroleum which benefited from the impact of oil prices due to conflicts in the Middle East.
For the majority of the remaining companies, prosperity is waning. Consensus expectations for earnings per share growth of the S&P 500 median stocks in the third quarter are only 9%, down from 14% in the second quarter. Analysts predict that "all sectors, except for information technology and communications services, will see a slowdown quarter-on-quarter." At the margin level, analysts have lowered their expectations for the third-quarter profit margins of the median stocks by 11 basis points since the beginning of this quarter, with "every sector, except for information technology, seeing a reduction."
Goldman Sachs' market breadth data also confirms this divergence: although the S&P 500 index is only 2% away from its historical high, the median stock is still 17% below its historical high, and market breadth has dropped to its lowest level since the internet bubble.
Three Major “Invisible Profit Killers”: Costs, Exchange Rates, and Profit Quality
Number One Killer: Rising costs of goods and energy erode profit margins.
The frequency with which S&P 500 companies mentioned "raw material costs" during earnings conference calls has risen to the highest level since mid-2022. Analysts at Bank of America point out that commodity inflation will limit profit margins in certain industries beyond expectations. In the third quarter, retail gasoline prices in the United States rose by about 30% year-on-year, exerting direct pressure on the cost sides of industries such as retail, transportation, and industrial products. Analyst Chris Nardone who specializes in consumer-oriented sectors noted that if oil prices remain high for a long time, profit margins will face continuous risks, and retailers may be forced to make a difficult choice between passing on costs to consumers and maintaining customer value.
It is worth noting that labor costs are the variable that has the greatest impact on the overall index profit margin. Labor expenses account for about 40% of the operating costs of American companies, while energy costs account for less than 5%. Bank of America believes that current wage inflation is on a cooling trend, which serves as an important buffer for overall profit margins. However, if energy prices continue to rise and eventually affect consumers, the downside risks in the fourth quarter and in 2027 cannot be ignored.
Second Killer: The capital expenditure narrative for AI remains unresolved, and the path to realization is still unclear.
The capital expenditures of hyperscale cloud computing vendors (Microsoft, Amazon, Google, Meta, Oracle) are expected to grow by more than 90% year-on-year in 2026, far exceeding any period in history, and the related capital expenditure forecasts for 2026 have been revised upward by 70% in the past year.
However, in 2026, the proportion of capital expenditures to operating cash flows for these companies exceeded 100%, and the divergence between free cash flow and net profit is widening. Bank of America warns that whether the investments in AI can be successfully monetized is a key variable for the sustainability of earnings, and that "the interactive effects among geopolitics, interest rates, and the technology industry may be underestimated by the market."
Large-scale software analyst Tal Liani pointed out that as we enter the third-quarter financial reporting season, the market's focus is on whether software vendors can convert customers' adoption of AI into substantial revenue growth. "Demand continues to exceed supply, and the pricing trend remains favorable," but Koji Ikeda also warns that the market will increasingly distinguish between companies that can truly achieve revenue growth from AI and those that rely solely on the AI narrative—"There will be a clear differentiation between the two."
Third Killer: The quality of profits is questionable, and one-time gains mask the true level of performance.
In the second quarter, earnings per share of the S&P 500 increased by 50% year-over-year, but when excluding the revaluation gains from private investments by Amazon and Google, the actual growth rate dropped to 32%. Bank of America pointed out that such revaluation gains "can also cause harm during valuation reversals" and are key variables that investors need to examine beyond the numbers in the financial reports. At the index level, the ratio of free cash flow to net profit has dropped to a historically low range, mainly due to the large-scale capital expenditures by super-large corporations putting pressure on their free cash flows.
2027 forecast: Optimistic consensus, while Bank of America is more cautious
The real stress test for the market lies in future pricing. The consensus expects the earnings per share of the S&P 500 to grow by 16% year-on-year in 2027, which is significantly lower than the 33% in 2026. Bank of America's forecast is even more conservative, at only 12%.
Bank of America strategists pointed out, “Historical data shows that when the earnings growth per share exceeds the trend level but begins to slow down, stock returns tend to be the weakest historically”—which is precisely where the current market is situated. At the same time, the consensus forecast for 2027 assumes that “except for the energy sector, there will be no contraction in earnings before interest and taxes (EBIT) across all industries.” Against the backdrop of high uncertainty in commodity prices, the fragility of this assumption is evident.
At the industry level, information technology (especially semiconductors) is expected to remain the main driver of index earnings growth in 2027, contributing about 80% of the growth. On the other hand, the communications services sector will face pressure of year-on-year negative growth due to the high base effect. Regarding bank stocks, Bank of America analyst Ebrahim Poonawala pointed out that the bank stock index BKX has fallen 12% since its mid-August high. Rising interest rates, doubts about the sustainability of the AI capital expenditure cycle, and concerns about AI disruption are the main restraining factors. "If the visibility of these issues can improve, there is room for valuation correction before the end of the year."
Overall, the fundamentals for this earnings season remain solid, but the market premium that "exceeded expectations" has significantly narrowed. For investors, the focus should shift from "whether it can exceed expectations" to "whether it can be maintained after exceeding expectations." Cost erosion, the monetization path of AI, and the profit assumptions for 2027 are the three key factors that will determine this outcome.