













"Ah, another American stock market crash?"
On November 20th, the major U.S. stock indices tumbled again. The cries of investors echoed as if from 15 days prior.
On November 5th, the NASDAQ Composite Index tumbled by 5.52%, but a few days later, the market rebounded strongly. Will the same scenario play out next week?
This time, the market seems even more complex. As of November 20th, Brent crude oil has risen by nearly 50% for the year, while spot gold has fallen by over 18%. Assets that were once highly sought after are now facing a realignment of prices.
A record-breaking IPO (initial public offering), which is regarded as the “barometer of sentiment in the AI (artificial intelligence) sector,” failed to “save” the AI stock.
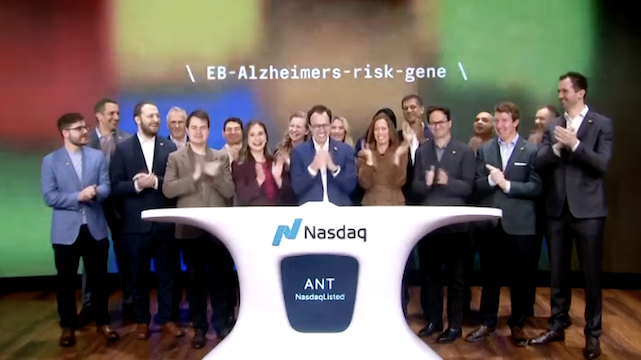
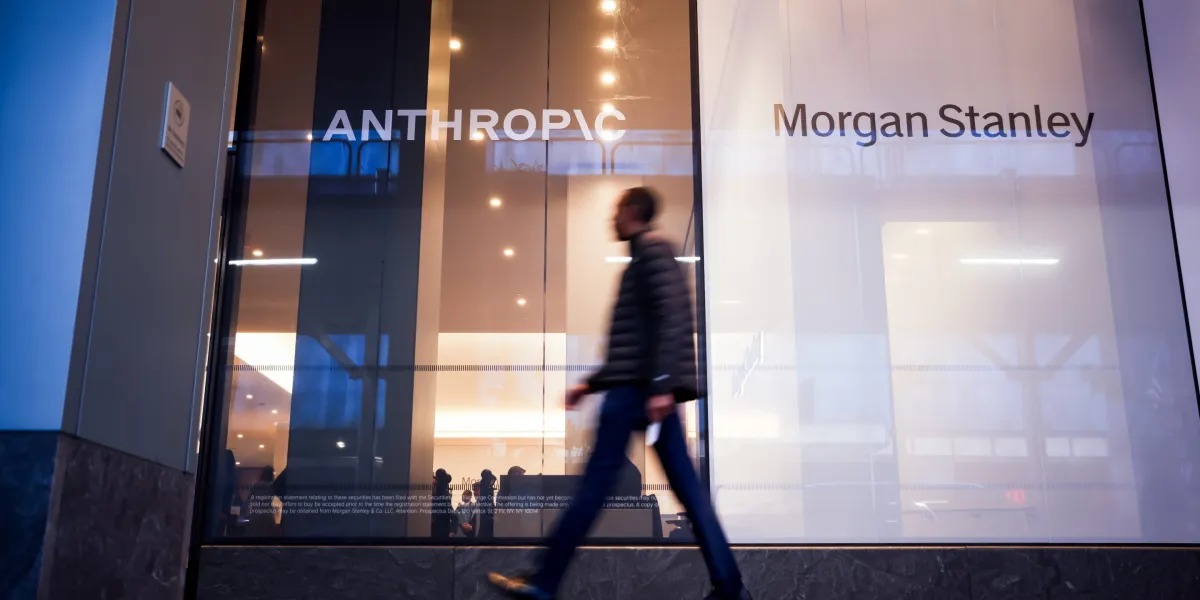
On November 19th, Anthropic, an American artificial intelligence research company that had been established for just over five years, went public on NASDAQ and secured a substantial amount of new capital. The following day, NVIDIA's stock price plummeted by about 14%, and the Philadelphia Semiconductor Index tumbled by 10.7%, causing another significant setback for global tech stocks. What is even more intriguing is that just three days prior, NVIDIA had just released financial results showing a doubling of its revenue year-over-year.
Good news has not entirely disappeared. However, looking back at the beginning of the year, one feels a sense of confusion—markets are no longer willing to pay the same prices as before for this kind of news.
At that time, global funds were still looking for their destinations: on one end, they were invested in AI to seek growth; on the other end, they embraced gold and U.S. Treasury bonds as a hedge against risks. Today, both AI and gold are under pressure, and some funds have returned to U.S. Treasury bonds.
The funds haven't disappeared, but it seems that the price is being recalculated over time: How much of a future does technology still have? How much money will be needed to reach that future, and how long will we have to wait?
Why did it fall again after the rebound?
Looking back at November 5th, the NASDAQ Composite Index tumbled 5.52%, the S&P 500 plummeted 4.36%, and the Philadelphia Semiconductor Index fell by over 12%. Following the U.S. mid-term elections, concerns arose regarding data center construction approvals, electricity costs, and regulatory prospects; Qualcomm's weak mobile chip business also added to the selling pressure on the semiconductor sector.
However, the market did not decline throughout the period. On November 6th, U.S. stocks began to stabilize, and on November 9th, there was a strong rebound: the S&P 500 rose by 2.35%, the Nasdaq Composite Index rose by 2.74%, and the Philadelphia Semiconductor Index rose by 6.9%. The decline in oil prices alleviated some inflation concerns, and buying on dips helped drive the upward movement. Nevertheless, NVIDIA still fell on that day, indicating that the rebound did not entirely rely on the leading AI stocks.
15 days later, a second wave of shock hit. On November 20th, the NASDAQ Composite Index tumbled by 5.28%, and the S&P 500 plummeted by 3.70%; the Philadelphia Semiconductor Index fell by a cumulative 17.1% within a week. Asian tech stocks also faced significant pressure on that day.
The two sharp declines had similar magnitudes, but the triggers for them were not quite the same.
This time, the pressure falls more heavily on the companies themselves. The management changes brought about by Jensen Huang's resignation have not yet been fully digested by the market, and then the media further disclosed that the U.S. Securities and Exchange Commission is investigating some of NVIDIA's accounting practices. At the same time, Anthropic, which held high hopes, approached its issue price on the day after its listing but failed to boost confidence in the AI sector.
From policy constraints on data center construction to corporate governance, compliance, and listing valuation risks, various news items have continuously impacted the market. Investors' doubts regarding the profit realization and capital returns of AI have also become more prominent.
Volatility changes have recorded this process. On November 5th, the VIX index ( VIX ) for U.S. stocks closed at 28.18; on November 9th, it dropped to 19.92; and on November 20th, it rose to 35.89. The MOVE index, which measures the expected volatility of U.S. Treasury bonds, also increased from around 86 on November 9th to around 106 on November 20th. Uncertainty in both the stock and bond markets is on the rise.
Gold has performed particularly abnormally. At the beginning of this year, international gold prices approached $5,600 per ounce, but on November 20th, they fell to around $3,520, a decline of over 30% from their peak. The US dollar, real interest rates, and investors' reduced demand for leverage could all be sources of pressure.
However, the funds seeking to hedge risks did not disappear. On that day, U.S. Treasury bonds rose, with the yield on 10-year Treasuries falling by about 10 basis points to around 4.95%. Gold and stocks both declined simultaneously, but there was demand for U.S. Treasury bonds, indicating that investors were reselecting hedging instruments. November 20th also coincided with the expiration of monthly options, and trading mechanisms such as market makers' hedging and leveraged funds reducing their positions could have amplified the decline. The actual impact of these factors still needs to be verified through data on holdings and transactions.
A market downturn can sometimes be just a matter of a few trading days, but the issue of capital returns cannot be resolved in just a few days. What best reflects such changes is an initial public offering (IPO) that is supposed to boost market confidence.
Two bills
On November 19th, Anthropic closed at $97.17 on its first day of trading. The next day, it hit a low of $83.05 during the session, just 5 cents short of breaking below its issue price, and ultimately closed at $88.91 (-8.50%).
It is true that a stock price falling back close to the issue price does not necessarily mean a failure in financing. According to the announcement from Anthropic, this round of IPO and concurrent private placements raised a total of approximately 119.5 billion US dollars.
What is more noteworthy is another set of financial statements. In the final prospectus, Anthropic disclosed that total committed expenditures for purchases, leases, and leases that have not yet begun to be fulfilled amount to approximately $900.9 billion, mainly related to computing power and infrastructure, with some arrangements extending until 2045. Of this amount, about $451.6 billion is expected to be incurred by the end of 2030; as of the end of September 2026, the related payment obligations expected to mature in the next 12 months amount to approximately $70.7 billion.
$119.5 billion is the total amount of this financing transaction for Anthropic; $900.9 billion represents contractual commitments to be fulfilled over several years and is not debt that has already been borrowed; approximately $70.7 billion consists of short-term payment arrangements calculated at a specific point in time. These three figures cannot be simply subtracted from each other, nor can it be concluded from this that there is a funding gap for Anthropic. The prospectus also reveals that before listing, Anthropic had approximately $146.6 billion in liquid resources.
The issue is not whether the company can pay the bills today, but whether future revenue growth will be able to continuously cover the costs of purchasing computing power, model development, and financing.
Anthropic reported revenue of approximately $17 billion in the third quarter, with costs for computing power and infrastructure amounting to around $9.9 billion. Although revenue has grown rapidly, it is still not sufficient to ensure that the investment returns for the next decade or so are already secured. Even if the usage of models continues to increase, if the price of inference services declines and training costs rise, the growth in revenue may not necessarily translate into profits in the same proportion. The efficiency of computing power utilization, the prices of model services, actual customer payments, and the pace of contract fulfillment could all affect these outcomes.
This listing also reveals another aspect of the capital relationships within the AI industry. Relevant parties such as Google, NVIDIA, AMD, Broadcom, Microsoft, Micron, and TSMC participated in a simultaneous private financing round totaling approximately $26 billion under Anthropic.
In response to this, investors may further inquire: How much of the company's growth actually comes from the real payments of end customers, and how much is based on mutual investments, long-term purchases, and credit support from industry partners? To answer this question, it is also necessary to verify the contracts and the actual payments made by end customers.
In contrast to Anthropic, there is NVIDIA. On November 17th, NVIDIA announced quarterly revenue of $115.8 billion, a year-on-year increase of 103%, with data center revenue reaching $107.6 billion. However, such achievements did not prevent the stock price from plummeting three days later. Jensen Huang's recent resignation has introduced new variables in corporate governance, but it cannot conceal the more widespread market issues.
One has already earned huge profits, while another has just received substantial financing. Yet investors are beginning to ask: How much capital will be needed to sustain the next round of growth?
Some analysts say that raising funds does not equate to making money, and current strong earnings do not automatically guarantee tomorrow's valuation.
Enter the central bank's sight
At present, such questions are coming into the attention of central banks from corporate financial reports.
Recent studies by the Federal Reserve and the European Central Bank have both focused on the debt, long-term procurement contracts, leasing, and guarantee relationships behind the expansion of the AI industry. The Federal Reserve's research mentioned potential off-balance-sheet obligations exceeding $3 trillion, while the European Central Bank's estimates for different sample companies exceeded $4 trillion.
Of course, since the two statistical methods are different, they should not be added together, let alone equated to the actual debt losses that have occurred. However, they point to a common issue: cloud service providers support data center construction through long-term procurement contracts, and project companies use these contracts to finance from banks, bond investors, and private lending institutions. When projects are delayed and the revenue from computing power falls short of expectations, the pressure of making payments and repaying debts may be transmitted along the contractual relationships.
For large platforms, long-term contracts can lock in computing power; for project companies that borrow to build data centers, the same contract may serve as a basis for financing. When projects are postponed, revenue may be delayed, but interest still has to be paid.
What's more challenging is that the three time frames do not align. For example, in terms of technical time, chips and models are rapidly iterating, so advanced equipment may need to be updated frequently. In terms of construction time, power access, data centers, cooling facilities, and approval processes often take several years. From a capital perspective, the due dates for equipment payments, interest, and debts will not automatically be postponed due to project delays.
Federal Reserve Board member Lisa Cook recently pointed out that American companies have announced specific data center construction plans worth over $2 trillion, but only a portion of these have actually been implemented. Federal Reserve Vice Chairman Philip Jefferson reminded that AI investments may first drive up demand for equipment, energy, and funds, while the broader productivity gains will only be realized later, following the adoption by companies and organizational adjustments.
This reminds one of the analysis by economist Carola Perez in "Technological Revolutions and Financial Capital": Financial capital often discovers, magnifies, and trades on the future value of new technologies faster than the production system does. It can support infrastructure construction, and may also cause valuations and financing scales to precede actual returns. Subsequently, capital and industry need to be realigned again.
However, historical theory is not a "basis" for determining market peaks. It is worth noting that what Perez describes is not the disappearance of technology, but rather the initial optimistic pricing of the future by financial capital, which must gradually be subjected to the test of reality regarding production, demand, and institutions. Perez also pointed out that AI is more appropriately understood as a further deepening of the information and communication technology revolution. The two sharp declines in the U.S. stock market in November are not sufficient to prove that AI capital expenditures have irreversibly peaked.
However, the credit market has already made adjustments in advance. Data from American Bank shows that from October 8th to 29th, the credit spread of commercial real estate mortgage-backed securities (CMBBS) rated AAA rose from 175 basis points to 195 basis points, while for those rated BBB, it increased from 400 basis points to 435 basis points. Capital did not withdraw entirely from AI infrastructure assets; instead, there was a demand for higher risk compensation for different credit ratings.
Scottish Asset Management's Chief Global Market Strategist Brian Levitt proposed another possibility: a slowdown in data center construction does not necessarily mean the end of the AI cycle; it could also alleviate some funding and interest rate pressures, allowing the investment cycle to extend.
The dividing line between the two scenarios is cash flow. If real demand and operating income continue to grow, investments can be sustained even after valuation adjustments; however, if financing tightens, leading to project delays, reduced equipment orders, and increased debt pressure, adjustments in the financial market may in turn slow down industrial expansion. At this point, what truly needs to be monitored are credit spreads, loan extensions, capital expenditure guidelines, and the progress of project implementation, rather than just focusing on the Nasdaq Composite Index or NVIDIA's stock price.
Technology continues to advance, yet capital has begun to recalculate the costs of reaching the future. Financial capital can purchase the future in advance, but it cannot cash in on everything for the future ahead of time.
(Author: Ouyang Xiaohong)